Institute for Tax Law

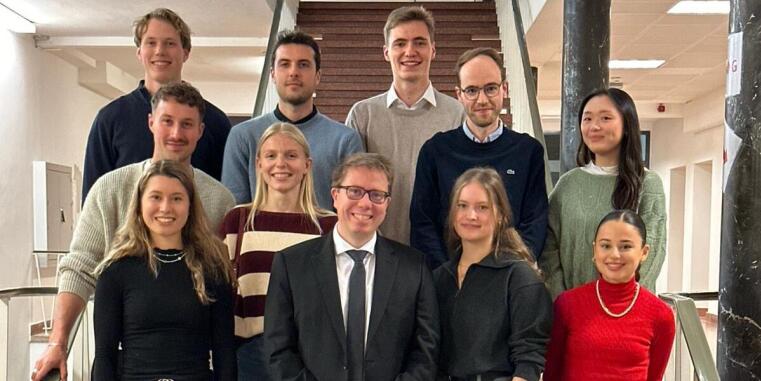
Welcome to the Chairs of Professor Dr Joachim Englisch and Professor Dr Marcel Krumm!

The Institute for Tax Law at the University of Münster was officially founded in 1934. On 12 April 1934, the Ministry for Science, Art and Education authorized Ottmar Bühler, who was the first holder of the chair, to use the term "Institut für Steuerrecht" (Institute for Tax Law) as the official name of what had formerly been known as "Seminar for Steuerrecht" (Seminar for Tax Law). Thus, the Institute for Tax Law is the oldest of its kind in Germany.

After Bühler retired, Friedrich Klein acted as Director from 1950 to 1974, before Paul Kirchhof, later Judge at the German Federal Constitutional Court, chaired the Institute from 1975 to 1981. In 1982, Dieter Birk was appointed Director and held the chair for almost 30 years. 

Since 2011, Joachim Englisch has been Director of the Institute; since 2018, he has shared the co-directorship with Marcel Krumm. 

Substantive rule of law calls for an equal distribution of the tax burden upon individual taxpayers. [...] The issues of tax justice are not transcendental; they need to be solved here, here and now.
Klaus Tipke
Reforming the tax system may not be easy or popular in the short term, but it holds out the prospect of significant economic gains and hence the promise of higher living standards in the long term.
Tax by Design – The Mirrlees Review
© Joachim Englisch

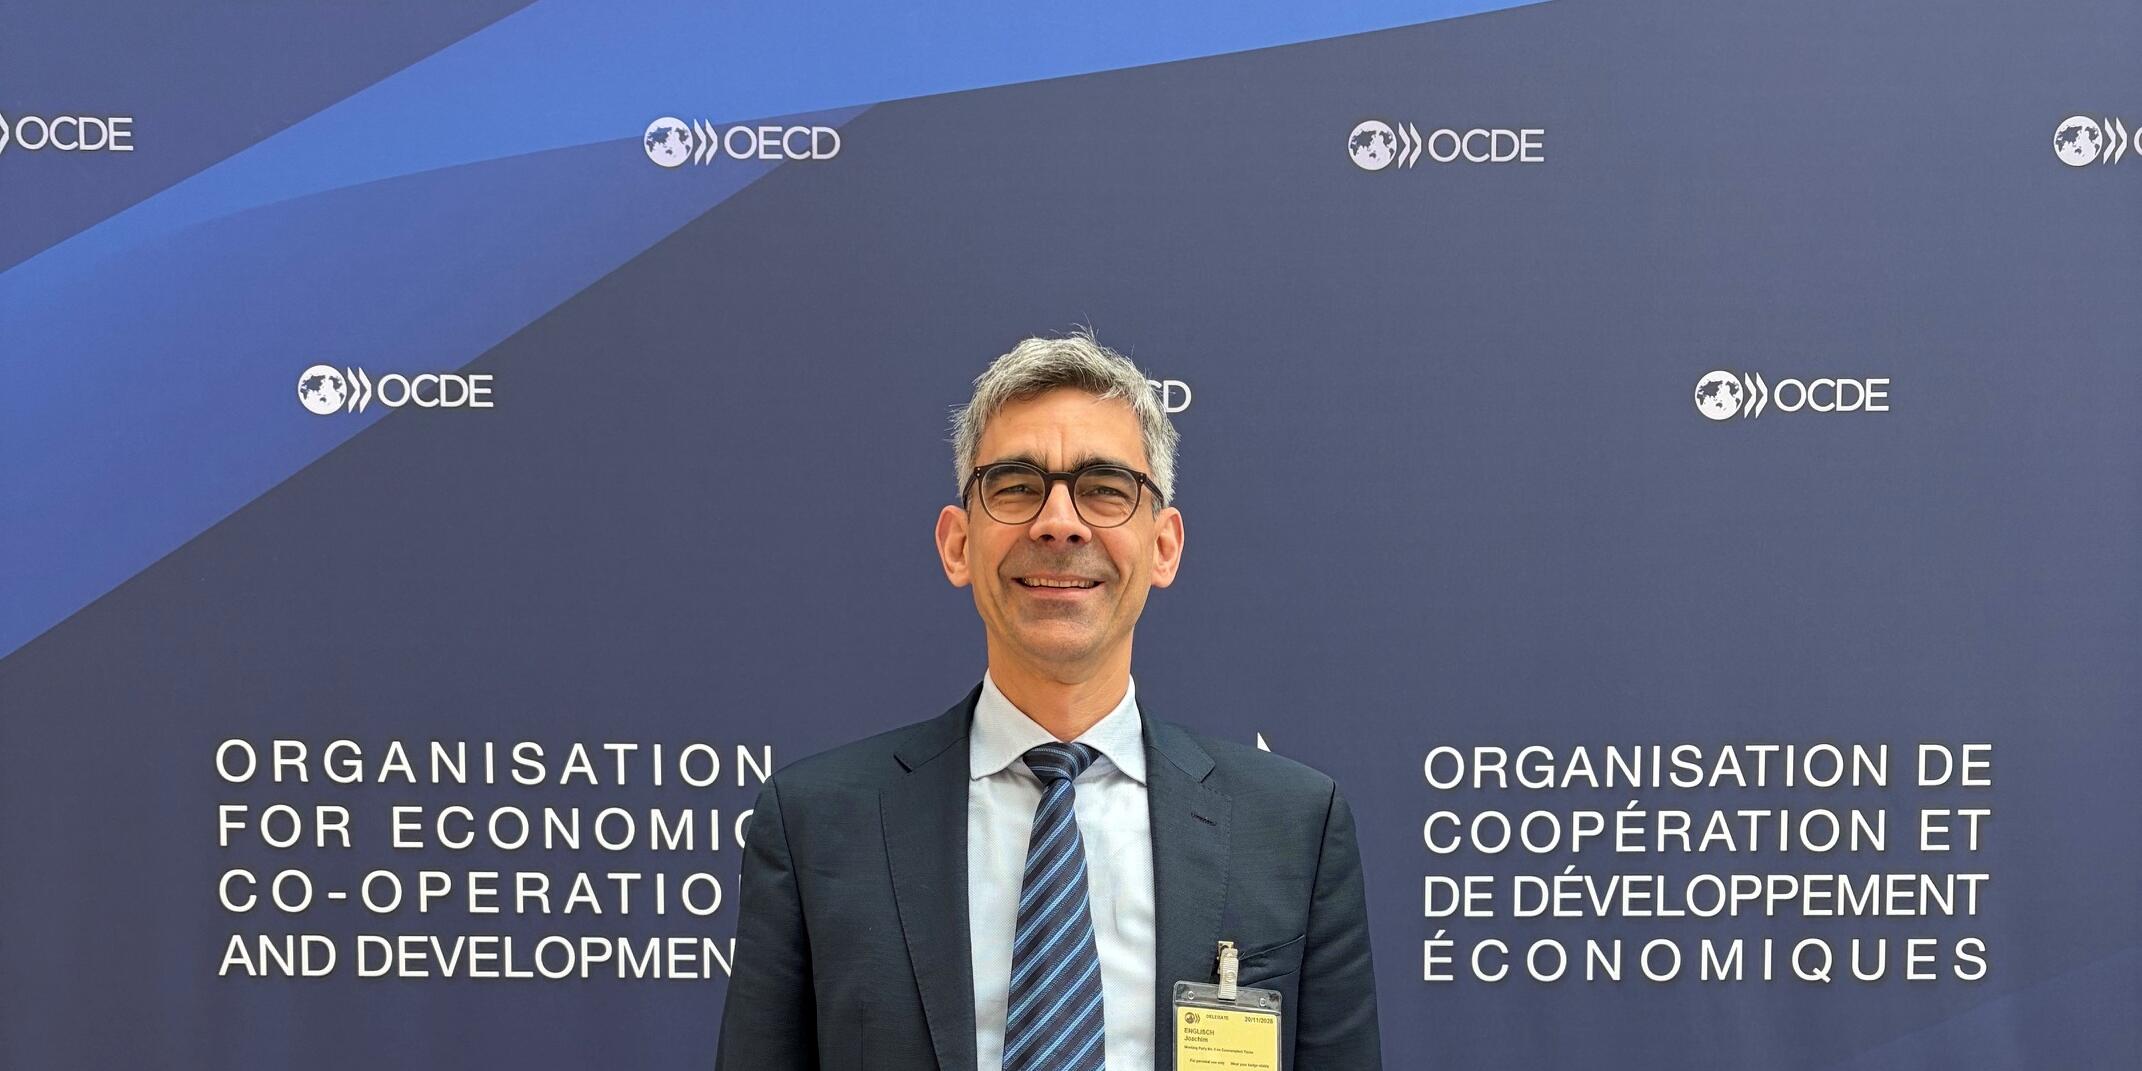
OECD WP9

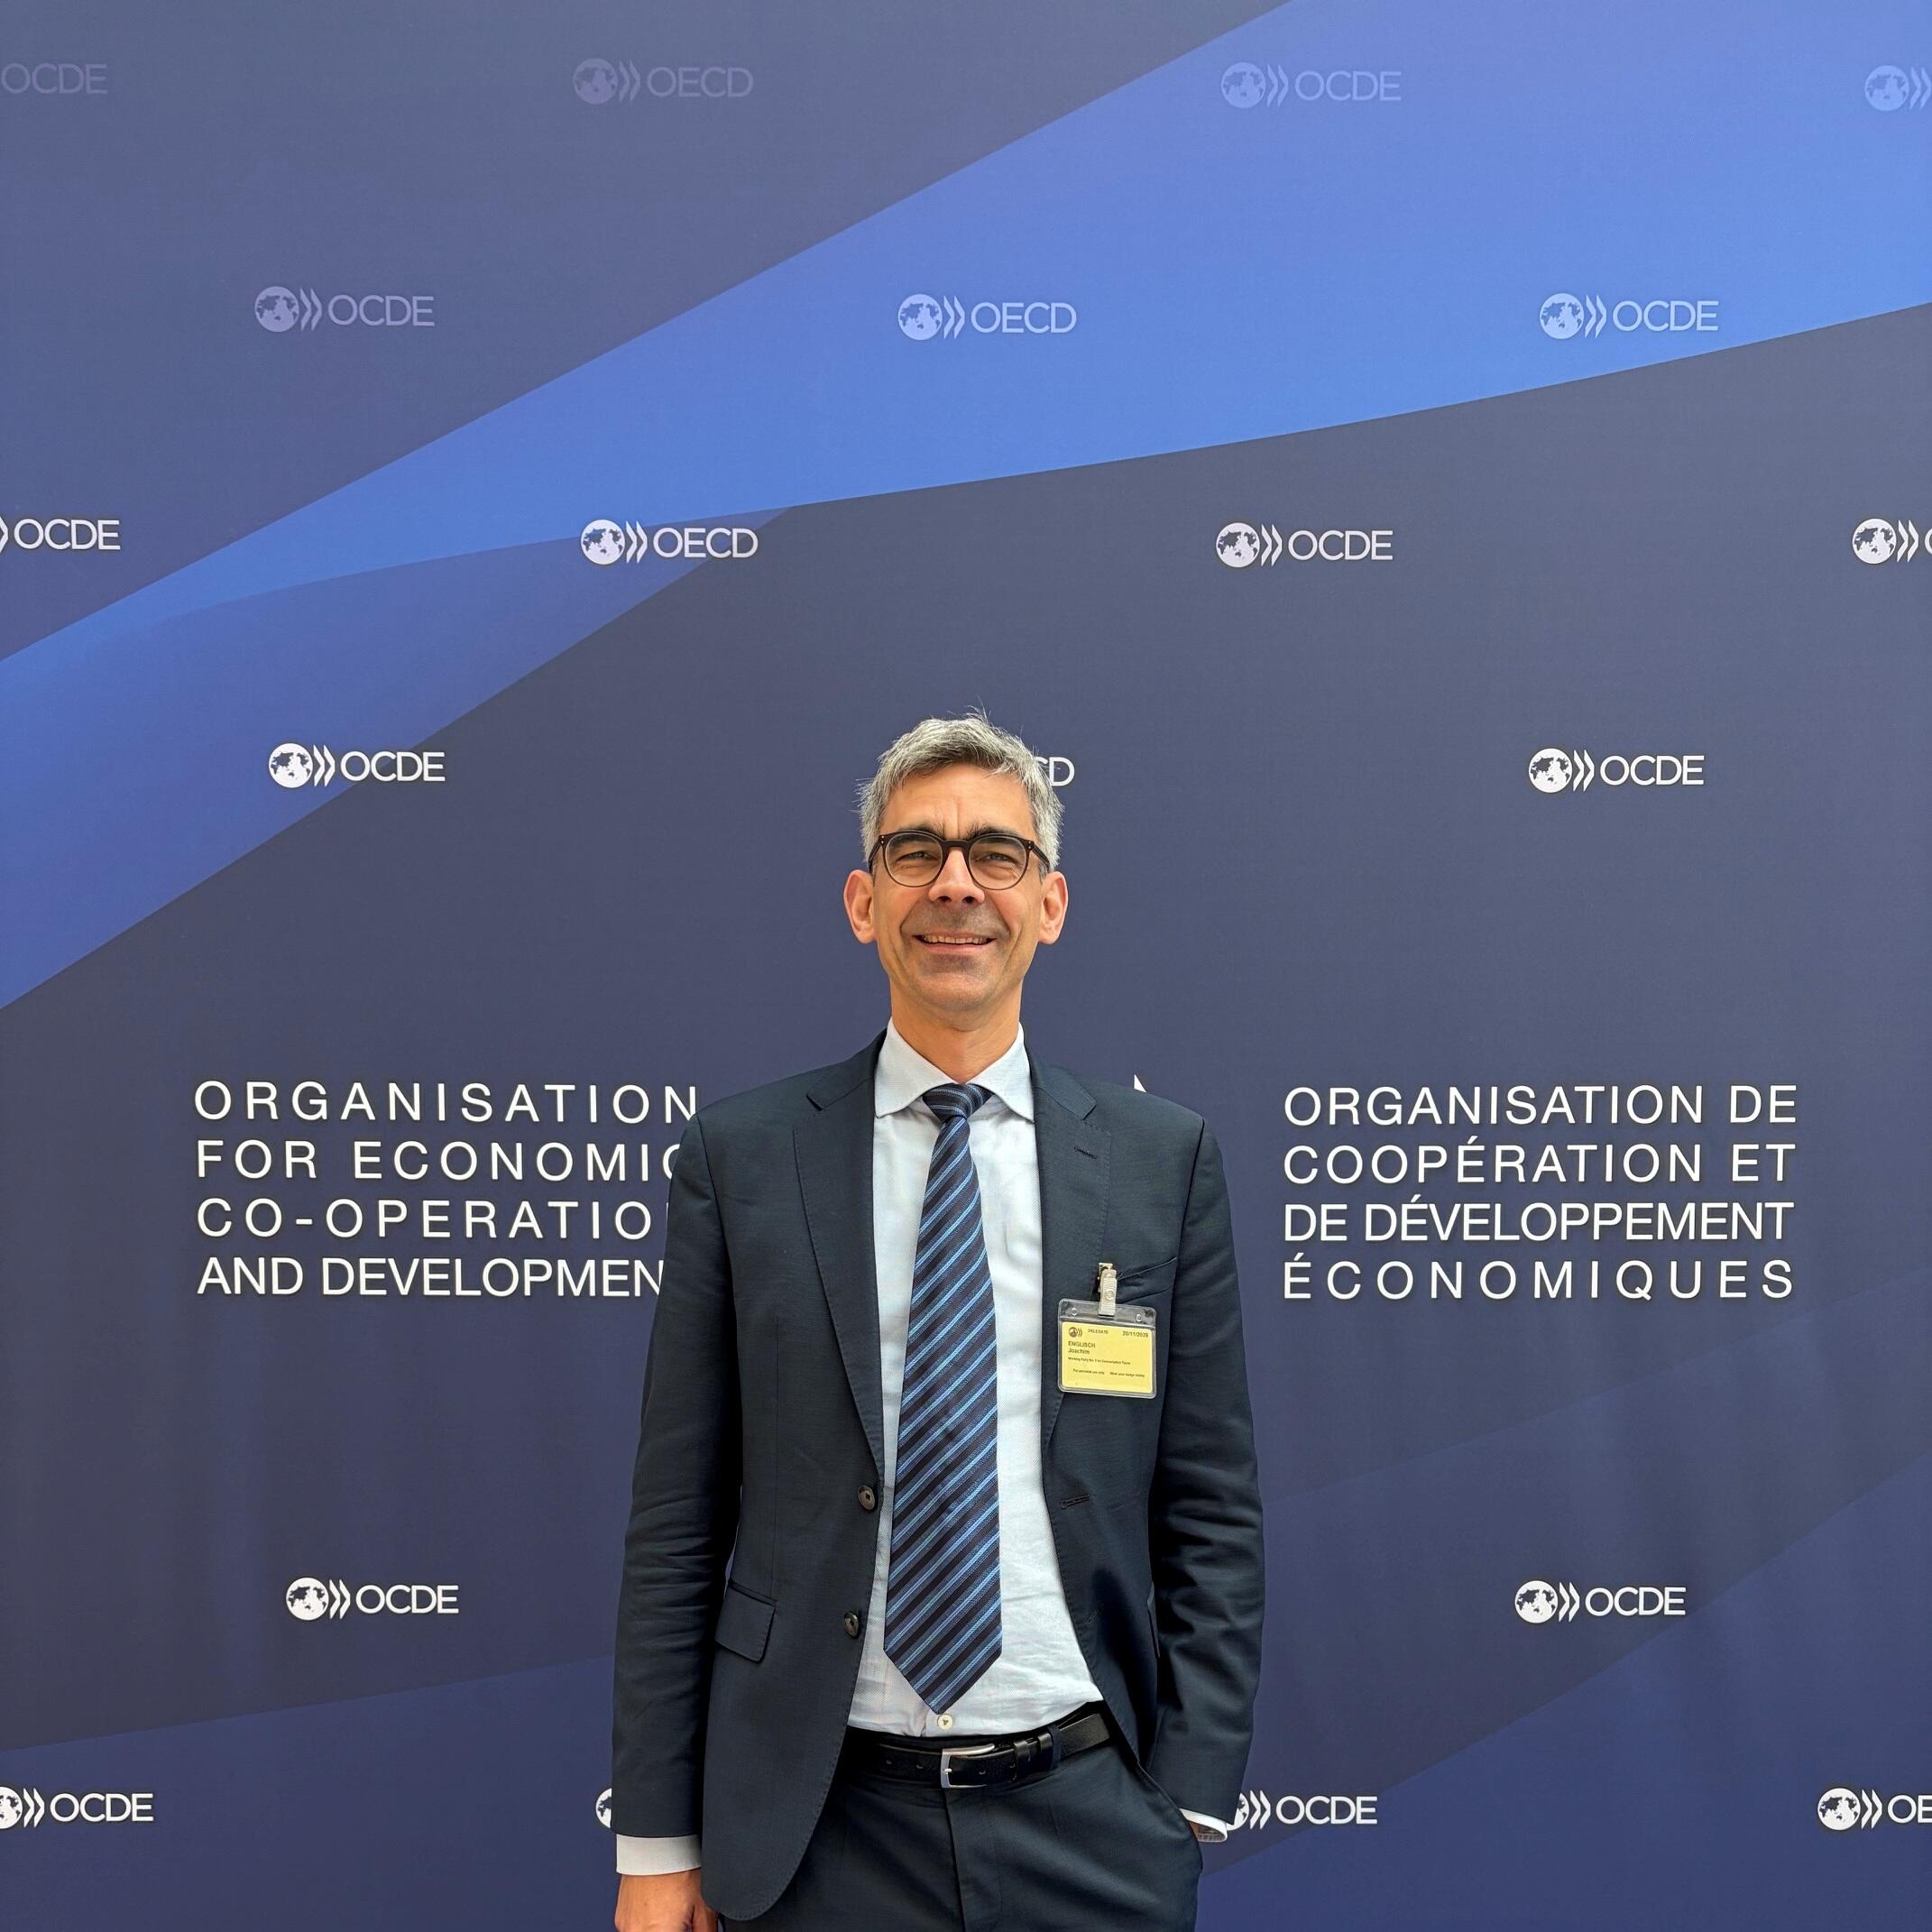
On 18–19 November 2026, Professor Joachim Englisch participated in a meeting of OECD Working Party No. 9 on Consumption Taxes (WP9). The discussions covered, inter alia, a framework paper and several discussion papers concerning the taxation of crypto-assets. The subgroup responsible for preparing these papers had previously consulted Professor Englisch in an advisory capacity.

EANOVAT PhD Seminar and Conference

On 12 November 2026, Prof. Dr. Englisch participated as one of the professors in the 11th PhD Seminar organised by EANOVAT (European Academic Network of VAT Experts), a network he co-founded. Held in Rome this year, the seminar provided seven doctoral candidates with the opportunity to present and discuss their research projects with peers and professors from across Europe.

The following day, Prof. Dr. Englisch opened the academic conference traditionally held in conjunction with the seminar, featuring presentations by a total of 14 scholars. The overarching theme of the conference was “Proportionality in VAT Law”, and Prof. Dr. Englisch chaired the panel on “Penalties”.
© Institut für Steuerrecht

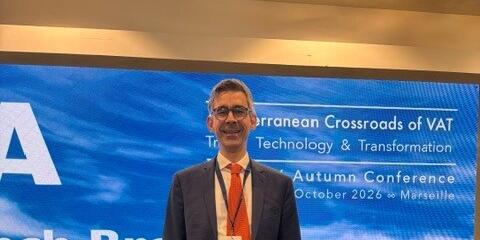
Presentation at the IVA Conference in Marseille

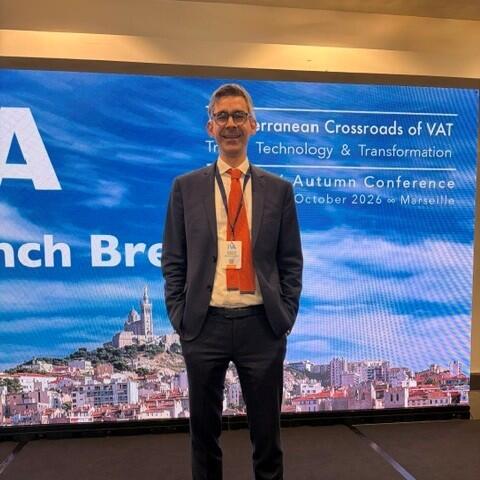
On 23 October 2026, Professor Englisch delivered a presentation at the annual conference of the International VAT Association (IVA) in Marseille. Together with a representative of the OECD, he discussed the taxation of different categories of tokens. Professor Englisch’s part of the presentation focused on the doctrinal and tax policy challenges of token taxation, particularly within the European VAT system. Special emphasis was placed on involving crypto marketplaces and exchanges in tax collection.

© Institut für Steuerrecht/J.-H. Schendel

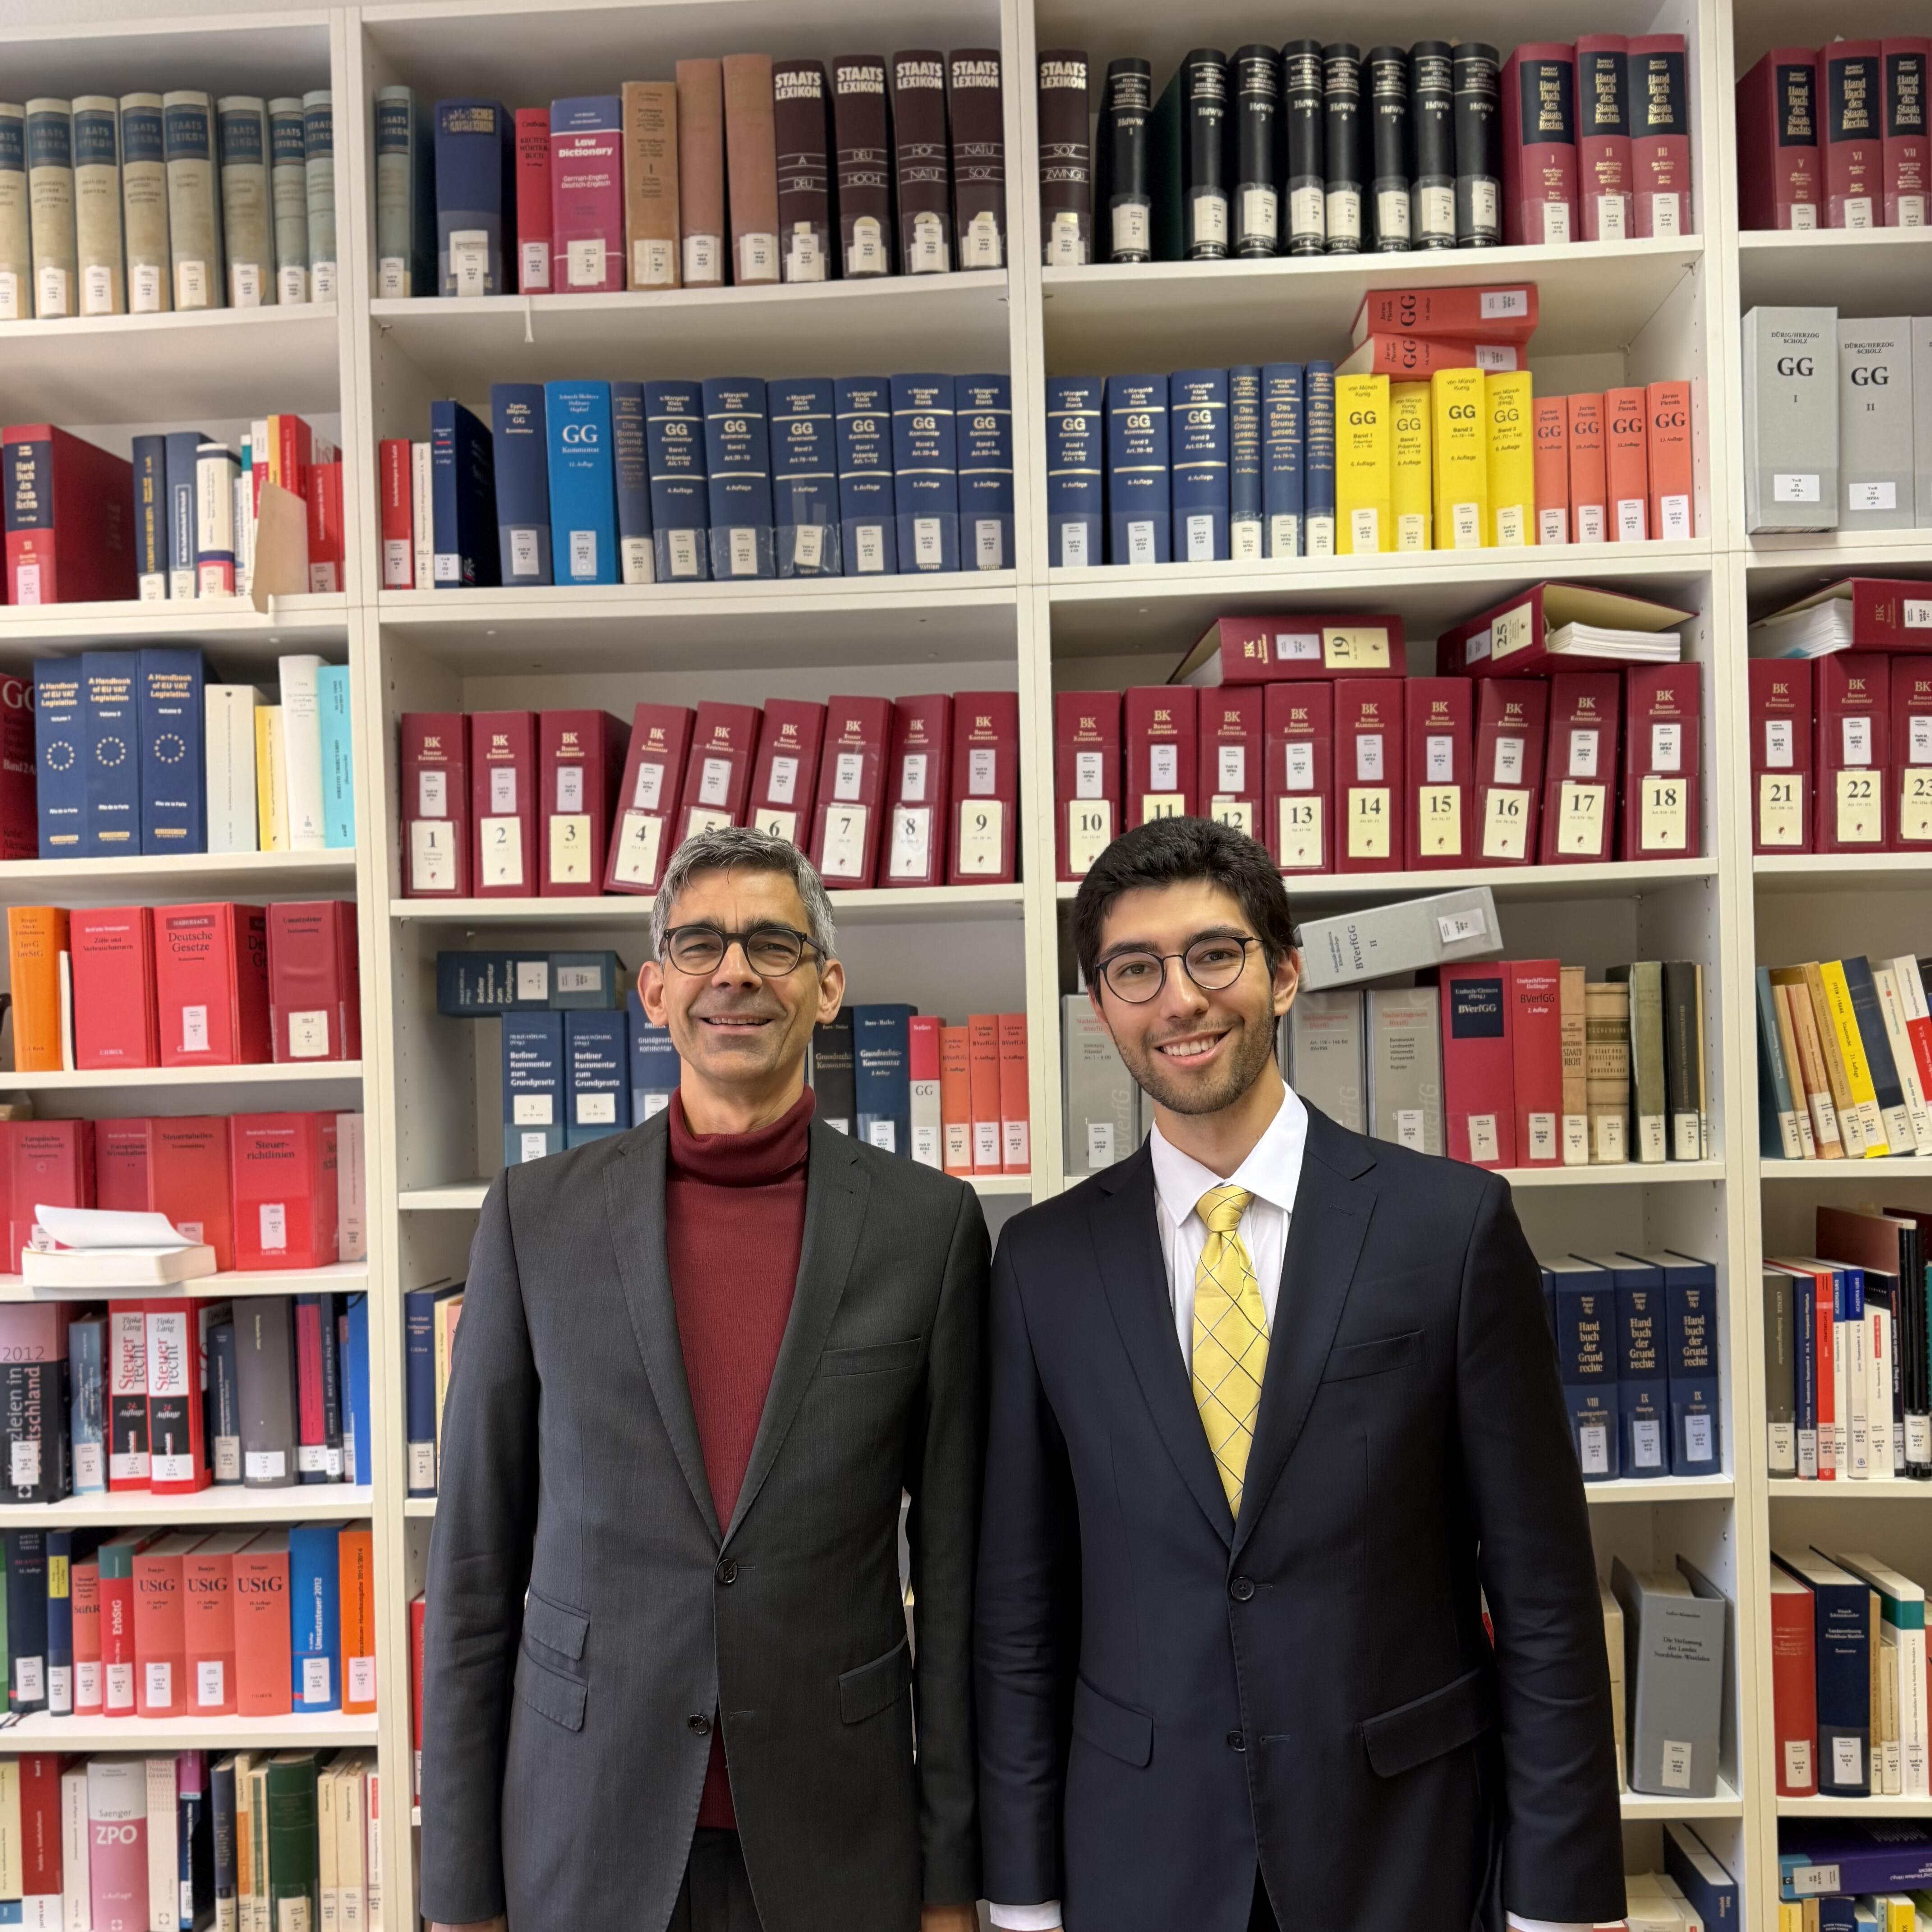
The Institute for Tax Law Welcomes Fábio Weber Ludwig as Visiting Researcher

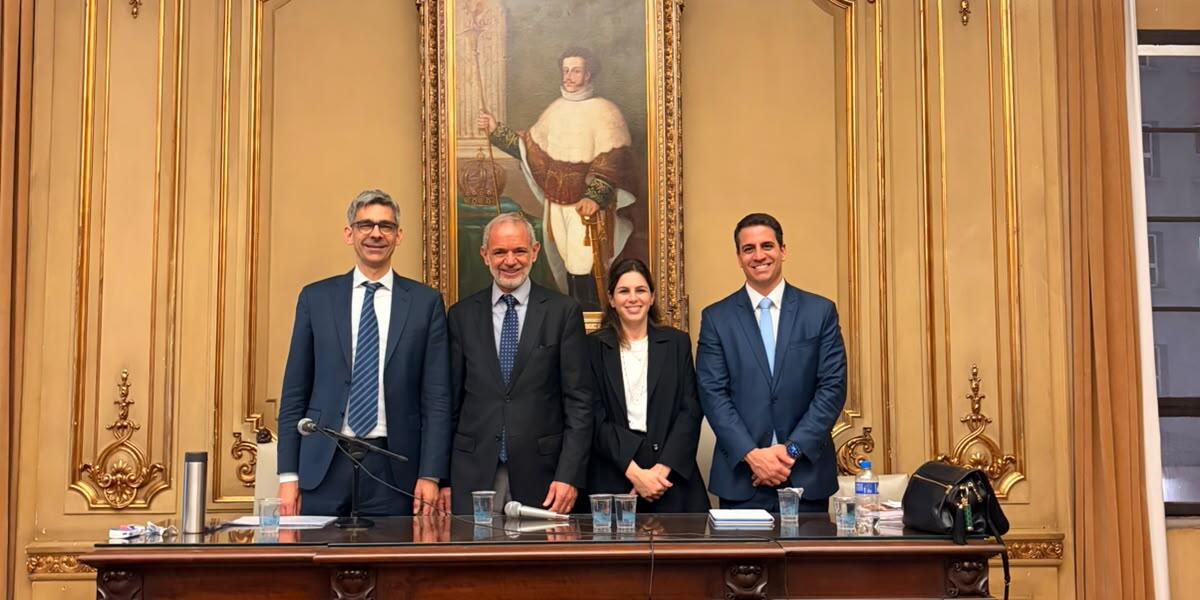
The Institute for Tax Law is pleased to welcome Mr. Fábio Weber Ludwig as a visiting researcher. Mr Weber Ludwig studied law in Brazil, specializing in tax law as well as civil law and civil procedural law, and practices as a lawyer in these fields. As part of his master’s thesis, Mr. Weber Ludwig is researching the progressivity of value-added tax (VAT), or the reduction of its regressive effects, which is enshrined in the Brazilian Constitution as an objective to be pursued when amending tax legislation. We warmly welcome Mr Weber Ludwig and look forward to a stimulating academic exchange!

© Joachim Englisch

Lecture at FGV Rio

Prof. Englisch was a guest at the Law School of FGV—Fundação Getulio Vargas—in Rio de Janeiro from October 5 to October 7. On October 6, he gave a lecture there for faculty and students on the topic “Taxation according to ability-to-pay as a constitutional principle.” This was followed by an extensive discussion that frequently drew on comparative law. Prof. Englisch also used his visit to launch a joint research project with colleagues at the FGV on the use of AI in the judicial system.

© Instituto Brasileiro de Direito Tributario

Presentation at the IBDT (São Paulo)

On October 1, 2026, Prof. Englisch gave a presentation at the Brazilian Institute of Tax Law (IBDT) in São Paulo on the implications and future of Pillar 2 minimum taxation. His key conclusions: We will have an international minimum tax system at least until the end of the decade, but it will be more fragmented than originally intended and reduced to a purely anti-BEPS instrument. Pillar 2 is no longer designed to meaningfully curb international tax competition beyond the transfer of profits without substance (“BEPS”). This brings so-called “decluttering” to the forefront; however, this requires a context-specific analysis to determine whether Pillar 2 serves as a replacement for or a supplement to the respective specific anti-abuse rule. The discussion with the three colleagues who commented on the presentation then focused on the income-based tax breaks that are popular in Brazil.

© Joachim Englisch

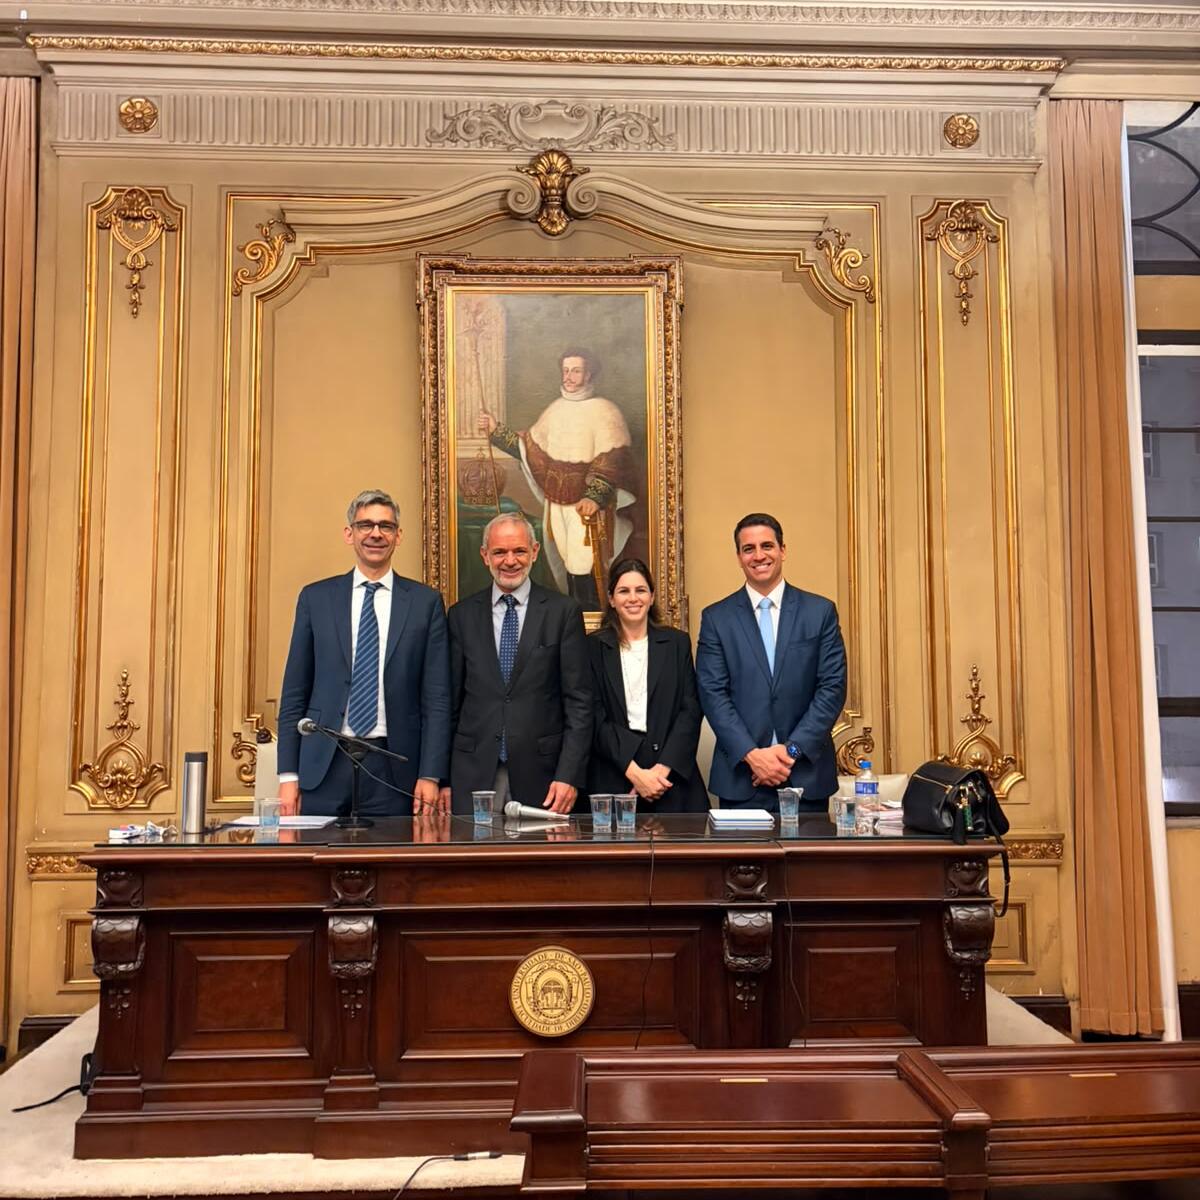
Lecture at USP (São Paulo)

On September 30, 2026, Prof. Englisch gave a presentation on “VAT and Crypto Assets” at our partner faculty at the University of São Paulo (USP). Following the presentation, his remarks were discussed by Prof. Vanessa Canada, who contributed to Brazil’s fundamental VAT reform implemented last year, and by Dr. Felipe Renault, the head of a Brazilian research group on the taxation of crypto assets. Afterward, there was an opportunity for a professional exchange with the host, Prof. Luís Schoueri, as well as with the audience. Prof. Englisch’s presentation was based on a research paper that was also accepted for publication in the "World Tax Journal" on September 30, 2026, following peer review.

IFA USA Virtual Panel

On September 17, 2026, Prof. Englisch participated as a panelist at the IFA USA’s 7th Annual Virtual International Tax Conference. Together with representatives from the European Commission, the U.S. Department of the Treasury, and the consulting industry, he discussed the topic: “Beyond BEPS: The Next Wave of International Tax Reform from Brussels, Paris, and New York.” His presentation focused on an analysis of the European Commission’s proposal for a “28th regime (EU Inc.).”

Contribution to liber amicorum: Value-Added Tax Issues Related to Stablecoins

In September 2026, Professor Dr Joachim Englisch contributed an article on Value-added tax issues related to stablecoins to the liber amicorum for Professor Dr Hans Nieskens. In it, Professor Englisch examines the technical background and the value-added tax treatment of the issuance and secondary acquisition of these tokens, which are backed by real assets and thus linked to their performance. At the level of taxable transactions, a distinction must be made between potential transactions by the issuer or seller, on the one hand, and those by validators or cryptocurrency exchanges, on the other. As a result, only a few transactions are subject to taxation; however, there is regularly a gap in enforcement on the anonymous, digital market. Relating to decentralized transactions, this enforcement gap is exacerbated by the lack of tailored value-added tax simplification tools, such as the deemed supply commission. Professor Englisch therefore recommends involving platform operators in the collection of value-added tax, following the model of DAC 8. The liber amicorum was presented to Prof. Dr. Hans Nieskens on 17th September, 2026.
© Joachim Englisch

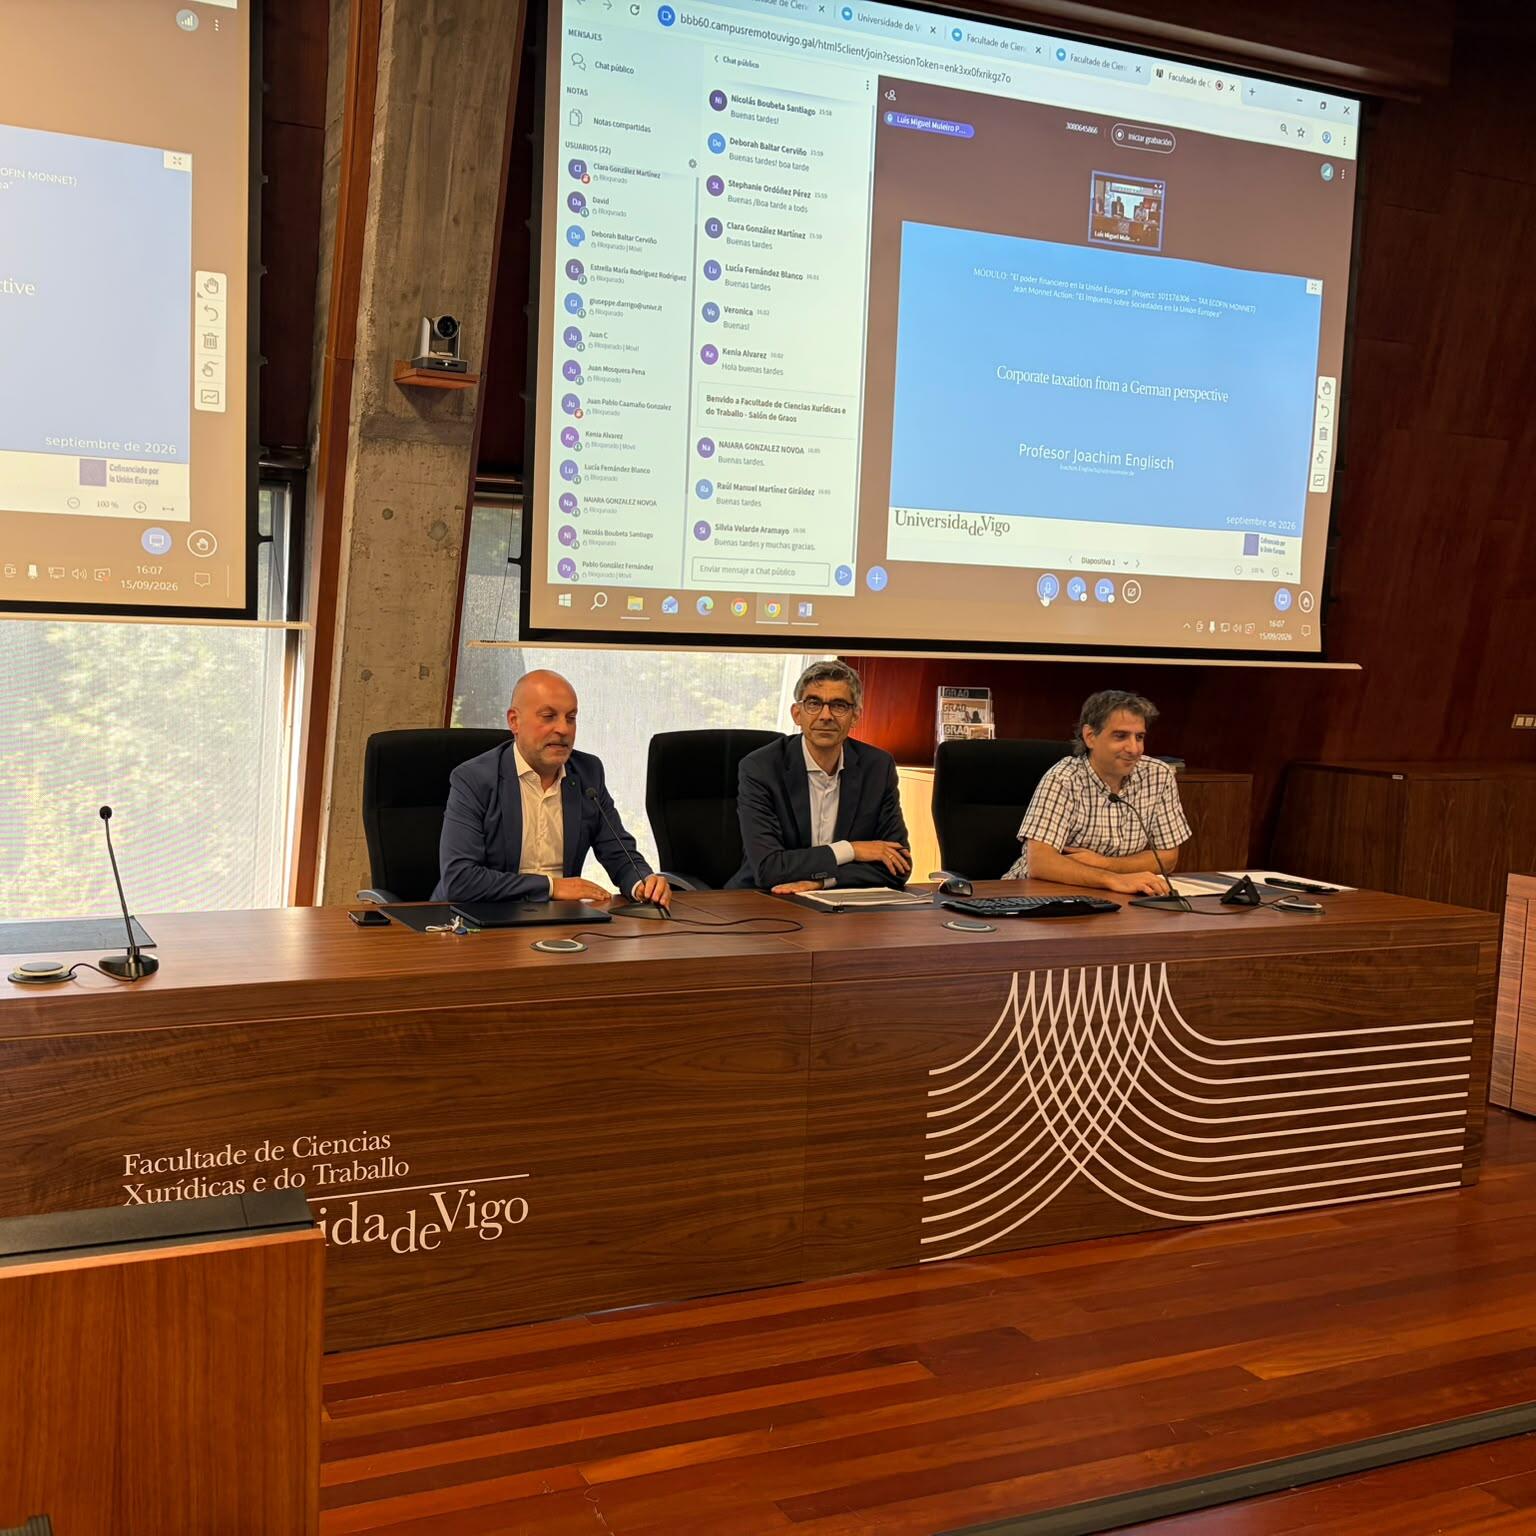
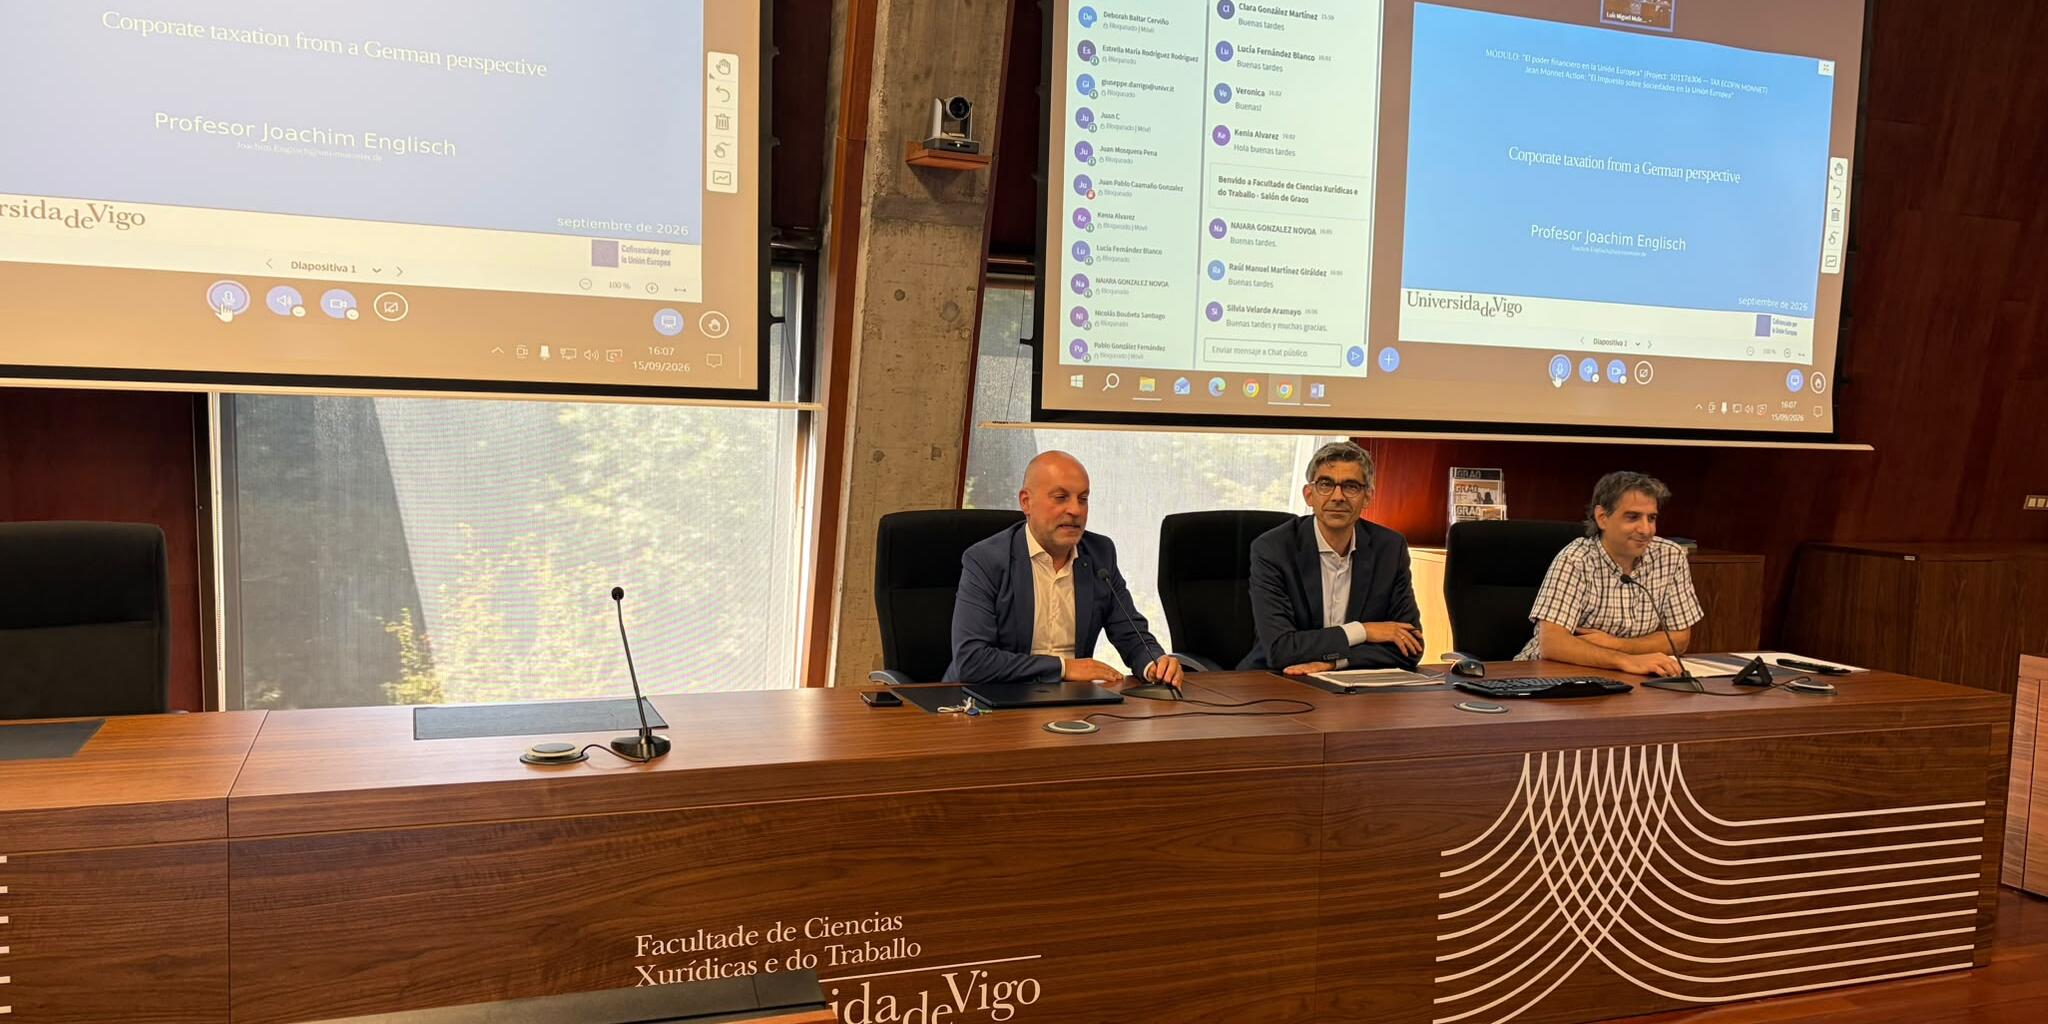
Lecture in Vigo, Spain

On September 15, 2026, Professor Joachim Englisch gave a half-day lecture on German corporate income tax law to students at the University of Vigo. The hybrid event was made possible by funding from the local Jean Monnet Chair. Numerous questions from the 40 participants, including several colleagues, provided an opportunity for an in-depth comparison with the Spanish corporate tax system.